
8 min read time

Table of Contents

What Is the Difference Between Full Coverage and Liability Insurance in Nevada?
The main difference between full coverage and liability-only insurance is that full coverage includes liability insurance and also covers damage to your own vehicle, regardless of who is at fault. Liability-only insurance covers the damage you cause to someone else's property and self, but it doesn't cover your own vehicle.
Full coverage policies generally include both collision (coverage for damages resulting from collisions) and comprehensive coverage (coverage for damages resulting from non-collision events).
Nevada's Minimum Liability Insurance Requirements
According to Nevada law NRS 485.185, Nevada drivers must have the following liability coverage to legally drive:
- $25,000 for bodily injury per person
- $50,000 for bodily injury per accident
- $20,000 for property damage
These limits are known as 25/50/20 coverage, and they are the minimum amount of liability coverage that Nevada drivers must carry.
Bodily Injury Liability Limits Explained
Bodily injury liability insurance is the base of any Nevada car insurance policy. It provides financial protection against claims brought by people who have been injured or killed as a result of a car accident caused by the insured driver.
The policy limits are stated as "$25,000/$50,000", where:
- The first figure ($25,000) represents the maximum amount that will be paid for bodily injuries to any single person in any one accident.
- The second figure ($50,000) represents the maximum amount that will be paid to two or more injured parties in any single accident.
Property Damage Liability Limits Explained
Nevada drivers must carry at least $20,000 in property damage coverage to cover damages to a person's vehicle or other personal property.
However, this $20,000 limit is often insufficient, as an accident-stemming car repair can easily exceed $5,000, and serious accidents can quickly push repair costs over $20,000.
Penalties for Driving Without Insurance in Nevada
The penalties for driving without insurance in Nevada can be severe. Here's what you might face if you're caught driving without it:
- License Suspension: The most immediate consequence is having your driver's license suspended. You'll need to provide proof of insurance to reinstate your privileges.
- Fines: Fines can range from $250 to $1,000, depending on the duration of the lapse and the number of prior offenses.
- Reinstatement Fees: These fees range from $250 to $750, depending on the length of the lapse and your driving history.
- SR-22 Requirement: If you go without insurance for more than 90 days, you'll need an SR-22 certificate, which is a certification that your insurer maintains active coverage for a minimum of three years.
- Habitual Offender Status: Repeated offenses within five years can lead to you being classified as a habitual offender, resulting in larger fines, longer license suspensions, and increased insurance rates.
- Vehicle Impoundment: Your vehicle may be impounded, adding towing and storage costs to your bill.
- Personal Liability: If you're involved in an accident without insurance, you may be personally liable for any damages or injuries, which could lead to significant financial loss.
- Criminal Charges: In some cases, driving without insurance may result in a misdemeanor charge, especially for repeat offenders.
Driving without insurance not only puts you at risk of financial and legal penalties but can also affect your insurance options, policy premiums, and future ability to drive.
Is Full Coverage Auto Insurance Required in Nevada
Nevada drivers do not need full coverage auto insurance. Instead, Nevada law requires drivers to have minimum liability insurance, as mentioned previously. This coverage is required to register a vehicle and legally drive on Nevada roads.
But full auto insurance coverage, or at least higher bodily injury limits, is recommended.
What Liability Insurance Covers
Liability insurance pays for injuries or property damage you cause to others in a motor vehicle accident. If you are at fault in an accident, this coverage may cover:
- Injuries to Other People: Medical bills, lost wages, and pain and suffering
- Damage to Another Person's Property: Repair or replacement of damaged vehicles, fences, mailboxes, or other property
- Legal Defense Costs: Attorney fees and court costs if you are sued for the accident
This coverage only applies if you are legally responsible for the accident and your own injuries or vehicle damage are not covered under liability insurance.
Injuries to Other People
Liability coverage helps pay for the medical costs of someone you injure, but only when you're responsible for the accident.
It can cover emergency care, hospital visits, ongoing treatment, and even lost wages or pain and suffering for the injured party. However, if you don't have enough coverage or the other driver's injuries are severe, liability limits may not cover the full cost, which could open up the risk of personal financial liability through things such as wage garnishment or asset sales.
That is why many people add underinsured motorist coverage or increase their bodily injury limits for more protection, in case they ever cause a severe accident.
Damage to Another Person's Property
Property damage liability pays for damage to other people's property if you're at fault in a car accident. If you're at fault and damage someone else's car or property, your insurance company will cover the other person's repair costs up to your coverage limit.
Legal Defense Costs
Even in Nevada, many drivers do not realize that their liability insurance policy covers legal defense costs under the duty to defend clause, not just compensation for damages. This is a big part of your coverage, as legal fees can quickly become expensive without insurance backing.
However, you should know that you can't pick your own defense attorney and will be appointed one by your insurer.
What Liability Insurance Does Not Cover
As stated before, liability insurance only covers damages you cause to others in a car accident, so there are many damages it doesn't cover.
The three main damages liability insurance doesn't cover are your medical bills, your property damage, and damage to your car from non-collision events.
Your Own Medical Bills
- What's Not Covered: Liability insurance's bodily injury coverage only pays for the injuries you cause to other people. If you are hurt in a crash where you are at fault, your own medical expenses are not covered by liability insurance.
- Solution: Having Med Pay coverage or PIP can allow you to cover medical expenses regardless of fault.
Repairs to Your Own Vehicle
- What's Not Covered: If you cause an accident, liability insurance will not pay for your car's repairs. Liability insurance covers damage you cause to the other party's vehicle or property, not your own.
- Solution: Having collision coverage, which is typically part of a full coverage plan, can allow you to cover damages to your vehicle regardless of fault.
Damage to Your Own Car from Non-Collision Events
- What's Not Covered: Liability insurance will not pay for damages to your vehicle from non-collision incidents, such as theft, vandalism, hail, flooding, fire, or hitting an animal.
- Solution: Comprehensive coverage pays for covered losses not caused by a collision. A deductible may apply.
What Full Coverage Auto Insurance Typically Includes
Besides carrying the base liability coverage, full coverage insurance also usually includes:
- Collision Coverage: Pays for damage to your vehicle in an accident, even if you're at fault.
- Comprehensive Coverage: Protects against non-collision events like theft, vandalism, natural disasters, and weather-related damage (e.g., hail or flooding).
One important thing full coverage doesn't usually include is medical payments coverage, which you must obtain separately and is just as important an investment as full coverage insurance, as medical bills can easily exceed vehicle repairs.
Collision Coverage
Collision insurance covers damage to your car that results from a crash, whether that's a head-on collision, a sideswipe, or a collision with a stationary object like a tree or a mailbox.
Unlike liability insurance, which pays for injuries and damages you cause to others, collision insurance protects you, the driver, from having to pay for repair bills when you are the one who caused the damage.
Comprehensive Coverage
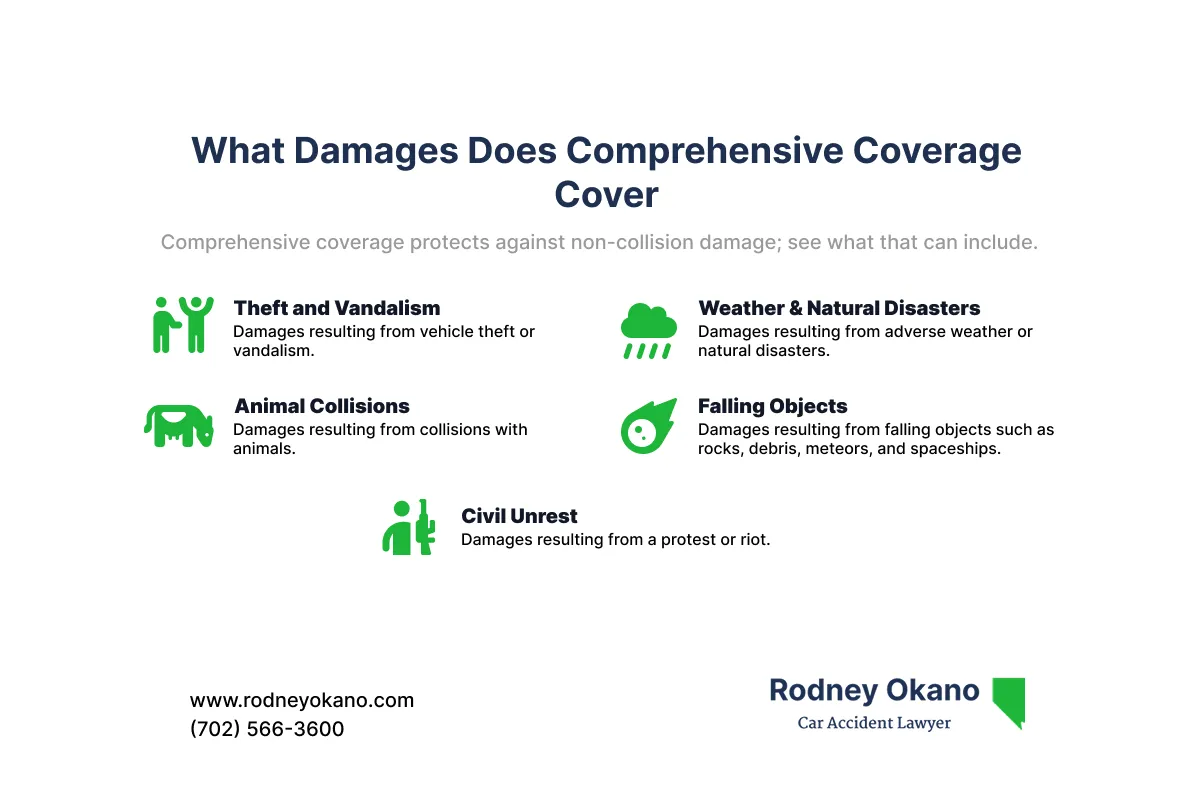
Comprehensive coverage protects against non-collision events that can significantly damage/affect your vehicle, such as theft, vandalism, and weather-related damage. This type of coverage can be very important in areas prone to natural disasters or in areas where car break-ins and thefts are high, which Las Vegas has many of.
Theft and Vandalism
Comprehensive insurance protects your vehicle against theft and vandalism, including the cost to repair or replace your car if it is stolen, up to your vehicle's actual cash value. This coverage is useful if you park your vehicle in high-risk areas or have a history of theft.
Weather-Related Damage & Natural Disasters
Comprehensive insurance also covers damage to your vehicle caused by severe weather, such as hail, wind, and floods. It can also protect your vehicle from damage caused by natural disasters, such as earthquakes, storms, and fires.
This protection can be important in areas prone to severe weather conditions and disasters.
Animal Collisions
Comprehensive insurance covers damage caused by collisions with animals, such as deer or other wildlife. This coverage is useful in rural areas where animal collisions are more common.
Falling Objects
Comprehensive coverage protects your vehicle from damage caused by falling objects, such as rocks or debris. For example, flying rocks from a gravel truck could strike your windshield while you're driving and crack it. Even in a bizarre case where a meteor crashes through your vehicle, comprehensive coverage will cover you.
Civil Unrest
Comprehensive insurance also covers damage caused by civil unrest, such as riots or protests. This can allow drivers to be more willing to flee potentially dangerous situations without the worry of their car holding them back.
Coverage for Leased Vehicles
If you lease your vehicle, your lessor may require you to carry comprehensive coverage to protect their investment. Without comprehensive coverage, your lessor may have to pay for repairs or replacement costs if your vehicle is stolen or damaged.
How Much Does Liability Insurance Cost in Nevada
Based on data from TheZebra, Insurify, MoneyGeek, and Experian, the average cost of state minimum liability insurance in Nevada is about $129 a month or $1,542 a year.
However, as most know, insurance premiums vary based on age, gender, marital status, credit score, and driving history, so someone who has a good credit score and driving record could be paying a premium hundreds of dollars less than someone with multiple at-fault accidents.
How Much Does Full Auto Insurance Coverage Cost in Nevada
Again, using data from TheZebra, Insurify, MoneyGeek, and Experian, the average cost for full auto insurance coverage (State minimum/Comprehensive/Collision) in Nevada is about $183 a month or $2,196 a year.
Like liability insurance, full-coverage prices vary by person because factors such as age and driving history affect rates.
What Is Underinsured/Uninsured Motorist Coverage
Uninsured/underinsured motorist coverage, also called UM/UIM coverage, pays for your medical bills, vehicle repairs, and other damages if you're in an accident with a driver who has no insurance or doesn't have enough coverage.
UM/UIM coverage is typically an add-on to auto insurance plans, but can be very helpful in hit-and-run situations.
Do Full Coverage Plans Include Underinsured/Uninsured Motorist Coverage
In Nevada, full coverage plans technically do not automatically include UM/UIM coverage, but insurers must offer UM/UIM coverage up to your bodily injury liability limits in any plan under NRS 690B.020, and you must explicitly deny it.
Is Underinsured/Uninsured Motorist Coverage Required in Nevada
UM/UIM coverage in Nevada is optional but highly recommended. UM/UIM coverage can be a lifesaver if you are involved in a collision with a driver who lacks insurance or carries insufficient coverage limits.
Contact Us Today
The Rodney Okano Law Offices is a Las Vegas Law Firm that specializes in representing those injured in motor vehicle accidents and those looking to become debt-free through Chapter 7 or Chapter 13 bankruptcy. Our firm has been in Nevada for over 20 years and has helped thousands with their car accident claims and bankruptcy filings. We offer a free attorney consultation, which can be set up by calling or sending an email inquiry.